The process
How an SBA 504 Loan Works, Step by Step
An SBA 504 loan works in four phases: prequalification, application, approval, and closing. The project is funded 50% by a bank first mortgage, 40% by an SBA-backed debenture through a Certified Development Company, and 10% by you. At NSDC, prequalification is fast, and most loans close within 45 days.
The 50–40–10 structure
Three parties, one building. Hover or tap a part to see it on the ring.
- 50% Bank or credit union First lien. Its own rate and term.
- 40% SBA 504 through NSDC Second lien. Fixed for 10, 20 or 25 years.
- 10% You Cash or equity you already hold.
The bank's half is a normal commercial first mortgage. It sets its own rate and term, and holds the first lien. NSDC's piece is funded by an SBA-guaranteed debenture, sold to investors once a month, which is why its rate is fixed for the whole term and set at funding rather than at approval. Your 10% is cash or, in some cases, equity you already hold in the property.
Two variants. A start-up, meaning a business operating two years or less, or a special-purpose property, puts in 15% and the SBA piece drops to 35%. Both at once means 20% down and an SBA piece of 30%. The bank's 50% never changes.
Who does what
Yes, you need both a bank and a CDC. That's the single most common confusion in the program, so here it is plainly.
First mortgage, 50%
Underwrites its own loan, holds the first lien, sets its own rate and term. Often the bank you already use. If you don't have one, we'll introduce you to lenders who do 504 deals every month.
SBA portion, 40%
Structures the deal, packages the SBA application, approves it in-house as a Premier Certified Lender, funds it through the monthly debenture sale, and services it for the life of the loan. What a CDC is.
Down payment, 10%
Bring the project, the financials, and the down payment. Answer questions once; we carry the answers to every form that needs them.
The four phases
Prequalify
What happens: a short conversation and four details: project size, property type, city, and how long you've been in business.
You provide: nothing else yet.
How long: fast. Free, and no commitment.
Who you talk to: a loan officer in Las Vegas or Reno, who stays on your file from here on.Apply
What happens: we build the application package with you and your bank, in stages, and structure the deal.
You provide: tax returns, current financials, a debt schedule, a personal financial statement for each owner, and the purchase agreement. The staged checklist.
Who you talk to: the same loan officer, plus your banker.Approve
What happens: underwriting and SBA authorization. As a Premier Certified Lender, NSDC approves in-house rather than routing every file to the SBA. That's where the time comes back.
You provide: answers to any follow-ups; usually few.
Alongside: appraisal and environmental review are ordered.Close
What happens: the bank loan and an interim second close together; the SBA debenture funds at the next monthly sale and your rate is fixed from then on.
Timeline: most of our loans close within 45 days.
After: you keep the same team for servicing. What happens after you close.
Why it closes within 45 days
The credential is the timeline. A CDC without Premier Certified Lender status sends each file to the SBA for approval and waits. NSDC underwrites and approves in-house under the PCLP program, which removes that queue from the middle of your deal. It's also why the loan officer who prequalifies you is the one who sees it through: there's no hand-off to a different office.
What you'll need at each stage
| Stage | What we'll ask for |
|---|---|
| Prequalify | Project size, property type, city, years in business |
| Apply | Business tax returns (three years) · personal tax returns · current profit and loss and balance sheet · business debt schedule · personal financial statement for each owner of 20% or more · purchase agreement or letter of intent |
| Approve | Anything underwriting flags: usually an explanation, occasionally an updated statement |
| Close | Insurance, entity documents, and the closing package your officer walks you through |
What can slow it down
We'd rather set this expectation now than on week three.
- Appraisal timing. Appraisers in busy markets book out. We order early.
- Environmental review. Some property types need a deeper look. Gas stations, dry cleaners and industrial sites are the usual suspects.
- Incomplete financials. Interim statements older than 90 days, a missing tax year, or a debt schedule that doesn't tie to the balance sheet are the most common reasons a file stalls.
- A seller in a hurry. Tell us the closing date in the purchase agreement on day one and we'll tell you honestly whether it's realistic.
A Nevada project, start to finish
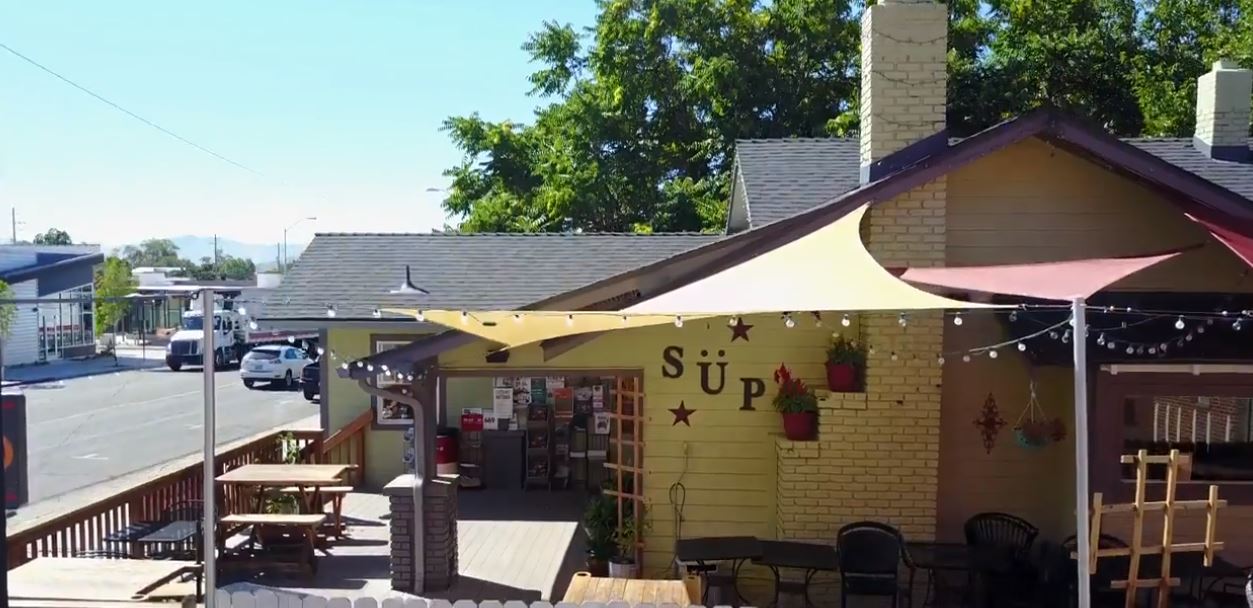
SÜP, Midtown Reno
A scratch-kitchen restaurant that bought its home on South Virginia Street with a $540,000 SBA 504 loan through NSDC, coordinated with Bank of America as the first-mortgage lender. Same four phases, same structure, a building the owners now hold.
Read the storyQuestions we get
How long does an SBA 504 loan take?
Do I need a bank and a CDC?
When is my rate set?
Can I apply before I've found a property?
This page is for general informational purposes only and does not constitute legal, tax, or financial advice. Loan terms and eligibility are subject to SBA guidelines and underwriting.
It sounds like a lot of paperwork. It's less than it sounds, and you don't do it alone.
You answer questions once. We carry the answers to every form that needs them.
Four details, no credit pull. A loan officer in Reno or Las Vegas reads them and calls you. Pre-qualification within three business days.
- Free
- No credit pull
- No documents to start
- A named officer replies
We love owning this because we're in charge of our destiny.
Full Tilt Logistics, NSDC borrower · 2,350+ loans since 1981