The program
SBA 504 Loans, Explained in Plain English
An SBA 504 loan finances owner-occupied commercial real estate and long-term equipment through three parts: a bank first mortgage for 50% of the project, an SBA-backed second mortgage at a fixed rate for 40%, provided by a Certified Development Company like NSDC, and a 10% borrower down payment. Start-ups and special-purpose properties typically put in 15% to 20%. Let's strip away the jargon.
What is an SBA 504 loan?
It's a long-term, fixed-rate loan for buying, building or improving the property your business operates from, or for heavy equipment with a long useful life. The U.S. Small Business Administration doesn't lend the money itself. It guarantees a bond, called a debenture, that funds 40% of your project through a nonprofit Certified Development Company. A bank lends the first 50%. You bring the rest.
The point of the program is the down payment. A conventional commercial mortgage typically wants a quarter of the price in cash. A 504 usually wants 10%. On a $1,000,000 building, that's the difference between $250,000 and $100,000 at closing.
- 50% Bank or credit union First lien. Its own rate and term.
- 40% SBA 504 through NSDC Second lien. Fixed for 10, 20 or 25 years.
- 10% You Cash or equity you already hold.
How the three pieces fit together
You need both a bank and a CDC. That's the most common confusion in the whole program, so we'll say it first. The bank makes a normal first mortgage, holds the first lien, and sets its own rate and term. NSDC, as the CDC, packages and approves the SBA portion, funds it through the monthly debenture sale, and services it for the life of the loan. Both loans close on the same property, usually on the same day.
Because NSDC is a Premier Certified Lender, the SBA piece is approved in-house rather than sent to the SBA and queued. That's the reason most of our loans close within 45 days. What a CDC is, and why one is in your deal.
What you can buy with one
Eligible
- An existing building your business will occupy (at least 51%)
- New construction you'll occupy (at least 60%)
- Land, as part of the project
- Machinery and equipment with a long useful life
- Renovation, parking, utilities
- Certain refinancing of existing commercial mortgage debt
Not eligible
- Rental or investment property you won't occupy
- Working capital on its own
- Inventory
- Property you're buying to flip
Rental property and the 504 · Construction with a 504 · Refinancing with a 504
What it costs
| Item | Figure | Notes |
|---|---|---|
| Down payment | 10% | 15% for a start-up (two years or less) or special-purpose property; 20% for both |
| SBA portion rate | 6.54% effective, 25 years | September 2026, as published by NSDC. Fixed for the full term. All terms and how the rate is set |
| Terms | 10, 20 or 25 years | Real estate is usually 20 or 25; equipment is usually 10 |
| Fees | roughly 3% of the SBA portion | Normally financed into the loan, not paid up front. The fee breakdown |
| Maximum SBA portion | $5 million | $5.5 million for manufacturers and qualifying energy projects; no cap on total project size. Maximum amounts |
Do you qualify?
Three tests decide it: your business is for-profit and under the SBA's size limits (tangible net worth under $20 million, average net income under $6.5 million); you'll occupy the building; and you're buying something on the eligible list. Most small businesses clear all three. The full requirements, with sources
How long it takes
- PrequalifyFast, free, no commitment
- ApplyWe build the package with you
- ApproveIn-house, as a Premier Certified Lender
- CloseMost loans close within 45 days
Nevada businesses that did this
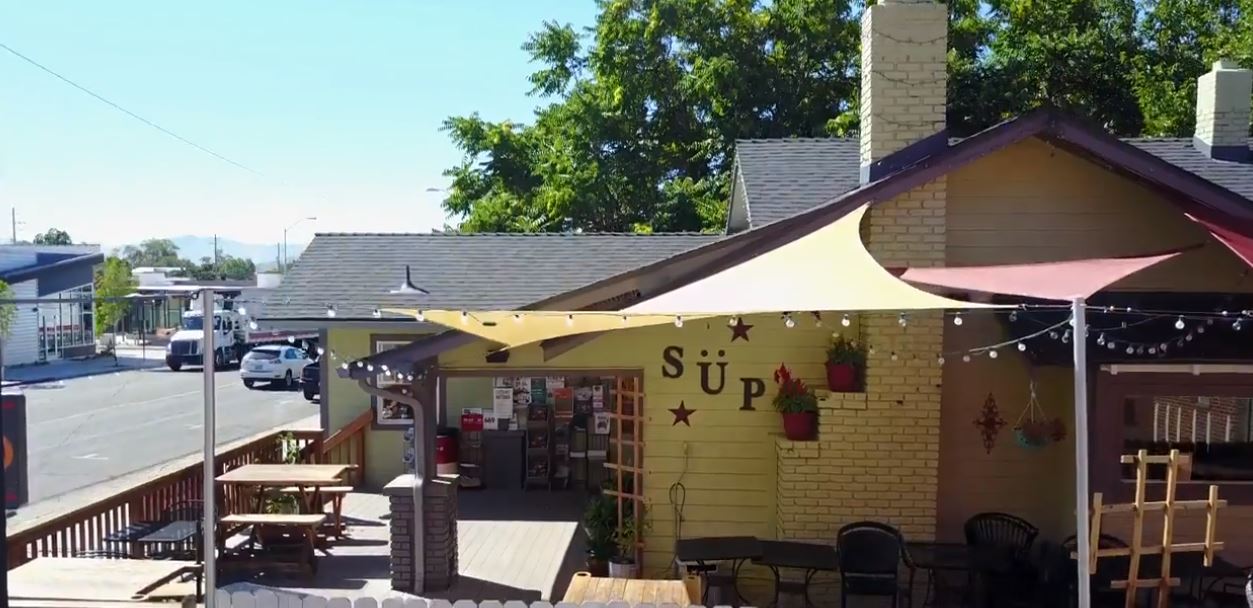
SÜP
$540,000
LV Iron & Steel
A family shop that owns its building.
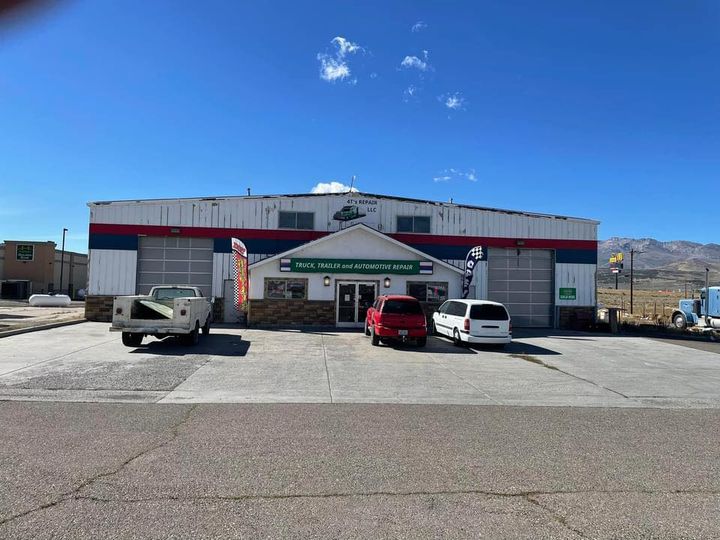
4T's Repair
Rural Nevada, same program.
Common questions
What are the disadvantages of an SBA 504 loan?
How hard is it to get an SBA 504 loan?
Can you pay it off early?
504 vs 7(a): which one?
What is a CDC?
How long does it take?
Keep reading
The rules
Do I qualify · Occupancy · Maximum amounts · Terms · Rental property
The money
Rates · Fees · Prepayment · The debenture · Calculator
The comparisons
504 vs 7(a) · 504 vs conventional · Owner-occupied real estate
The projects
This page is for general informational purposes only and does not constitute legal, tax, or financial advice. Every figure is dated and sourced; SBA rules change, and this page is re-verified after each SOP update.
This isn't too complicated to start. Starting is one phone call.
Las Vegas (702) 877-9111 · Reno (775) 770-1240
Four details, no credit pull. A loan officer in Reno or Las Vegas reads them and calls you. Pre-qualification within three business days.
- Free
- No credit pull
- No documents to start
- A named officer replies
We love owning this because we're in charge of our destiny.
Full Tilt Logistics, NSDC borrower · 2,350+ loans since 1981