
SBA 504 loans · Nevada · Since 1981
Stop paying for someone else's building.
NSDC is Nevada's nonprofit SBA 504 lender. We fund the piece of your building the bank won't.
Every month, your rent buys your landlord a little more of the building your business runs on. An SBA 504 loan flips that: 10% down, a rate on the SBA portion fixed for up to 25 years, most loans closed within 45 days. A building your business can grow into. A location nobody can raise the rent on.
Four details, no credit pull. A loan officer in Reno or Las Vegas reads them and calls you. Pre-qualification within three business days.
- Free
- No credit pull
- No documents to start
- A named officer replies
We love owning this because we're in charge of our destiny.
Full Tilt Logistics, NSDC borrower · 2,350+ loans since 1981
Everything you need to own instead of rent, in one loan.
Here's exactly what a 504 through NSDC gets you, and what each piece means for the business.
The building, with 10% down
A conventional lender wants a quarter of the price in cash. A 504 wants ten percent. On a $1M building that's $150,000 that stays in your business.
So the cash a bank would take at closing stays in the business: a hire, a machine, inventory.
The math
A rate that never moves
The SBA portion is fixed the day it funds, for the whole 10, 20 or 25 years. No reset, no balloon, no surprise in year seven.
So your occupancy cost in year twenty is the same as in year one.
This month's rate
Closed within 45 days
As a Premier Certified Lender, NSDC approves in-house. Your file doesn't sit in a queue at the SBA.
So you can put a real closing date in the purchase agreement.
The four phases
The same team for 25 years
We service every loan we close. The person who prequalifies you is the team you call in year twelve.
So you're never handed to a stranger who bought the servicing.
After you closeIs this for you?
Five checks. Most Nevada businesses clear all five.
- Your business operates for profit.
- You'll occupy at least 51% of an existing building, or 60% of a new one. Tenants can have the rest.
- Tangible net worth under $20 million.
- Average net income under $6.5 million.
- The money buys, builds, refinances, or equips the place you work from. Not investment property, not working capital alone.
Newer business? Not out. Different: operating two years or less, you'll typically put in 15% instead of 10%.
“We don't have to worry about a landlord giving us a 60-day notice, rent hikes, any of that. We love owning this because we're in charge of our destiny.”
Full Tilt Logistics, NSDC borrower
- 50% Bank or credit union First lien. Its own rate and term.
- 40% SBA 504 through NSDC Second lien. Fixed for 10, 20 or 25 years.
- 10% You Cash or equity you already hold.
How it works
Three parties. One building. You bring ten percent.
The bank takes the first half on its own terms. NSDC delivers the SBA-backed 40% at a fixed rate. You put in 10%. That's the whole structure, and it's the reason a business that could never write a $250,000 check can own its building anyway.
- You get two loans on one building. The bank's, and the SBA's, which NSDC arranges.
- You talk to NSDC first. We bring a bank that does 504 deals every month, or we work with yours.
- You don't structure any of this. You tell us about the building. We do the rest, through closing.
- 1
Review
You send four details. A loan officer says whether a 504 fits, within three business days.
- 2
Structure
We set the bank / SBA / you split for your building and bring the bank in, or work with yours.
- 3
Approve and close
We package for the SBA and approve in-house. Full approval typically takes two to three weeks. Most loans close within 45 days.
- 4
Own
The SBA portion is fixed the day it funds. We service it, from the same office, for the life of the loan.
The cost of doing nothing
“I've been renting forever and I have nothing to show for it.” We hear it every week. Here's the deal, in one table.
Every renewal you sign is another lease term building your landlord's equity instead of yours.
| Keep renting | Conventional loan | SBA 504 | |
|---|---|---|---|
| Cash to get in | A deposit, then rent forever | $250,000 (25%) | $100,000 (10%) |
| What the rate does | Rises at every renewal | Resets in 5–10 years | Fixed for up to 25 years |
| How long you have it | Until the landlord decides | Often a 10-year balloon | 10, 20 or 25 years, no balloon |
| Who you deal with after | The landlord | Whoever buys the servicing | The same NSDC team |
| Who owns it at the end | Your landlord | You | You |
Four details, no credit pull. A loan officer in Reno or Las Vegas reads them and calls you. Pre-qualification within three business days.
- Free
- No credit pull
- No documents to start
- A named officer replies
We love owning this because we're in charge of our destiny.
Full Tilt Logistics, NSDC borrower · 2,350+ loans since 1981
Why NSDC, not just why own
Four reasons the deal goes through us.
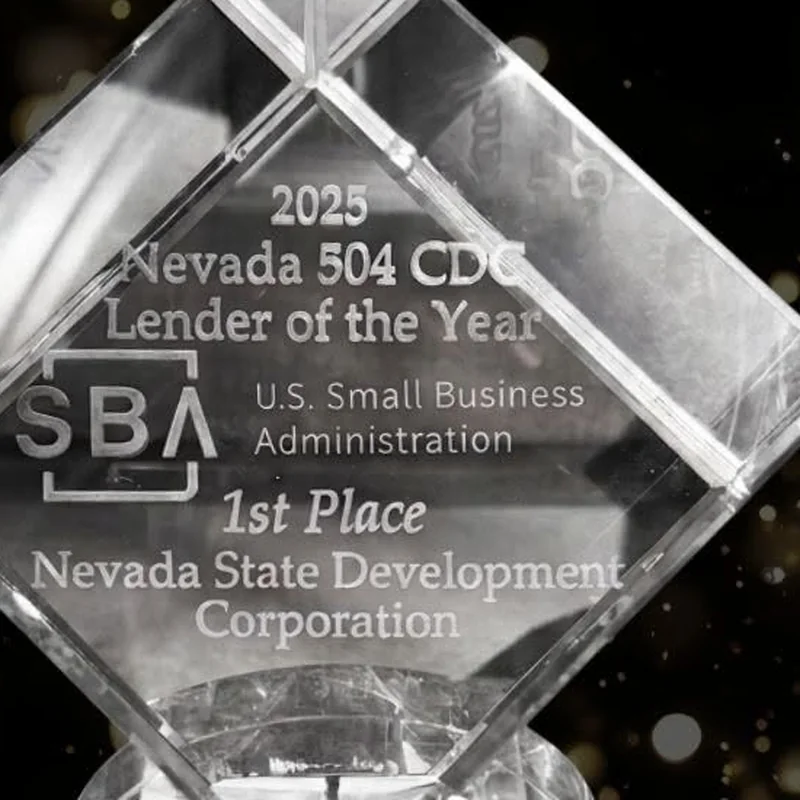
- Nevada's #1 SBA 504 CDC. Named by the SBA Nevada District Office, 2025. The oldest, largest and only statewide CDC in the state.
- 2,350+ loans since 1981. $1 billion+ in SBA financing to Nevada businesses.
- The same team for 25 years. Offices in Las Vegas and Reno. The officer who prequalifies you is the team that services you.
- We tell you when a 504 isn't your loan. And which one is. Sending you to the right loan is how we earn the referral later.
What you get
Six things NSDC does for you.
- A straight read on fit, within three business days
- The structure worked out for your building
- A bank brought in, or yours used
- The SBA package prepared, submitted and approved in-house
- Closing coordinated with the bank and the title company
- Your SBA loan serviced by the same office for its whole life
Proof, not promises
We've done this more than 2,350 times in Nevada.
Every number here is one NSDC has published. Every story on this site links to the real business. We'd rather show you the record than tell you about it.
The businesses that stopped rentingSource: figures NSDC has published, verified September 2026.
Pick your situation. We'll tell you straight if a 504 fits.
Including when it doesn't. Sending you to the right loan is how we earn the referral later.
You're renting the building you'd rather own.
This is the deal the 504 was written for. You occupy at least 51%, you put in 10%, and the SBA portion is fixed for up to 25 years. Lease out the rest if you want; the rent helps carry the loan.
Your likely route: a 504 purchase loan, 10% down.
How it works on a $1M building
Ground-up construction, financed from the plans.
You occupy 60% of the new building. The bank carries the build on an interim loan; the SBA debenture takes it out at completion and fixes your rate that day. We'll tell you honestly what makes construction slower and what can go wrong.
Your likely route: a 504 construction loan. The bank carries the build; the SBA portion fixes at completion.
Building with a 504
A balloon coming due, or a rate about to reset.
Refinance eligible commercial mortgage debt at a fixed rate, up to 90% loan-to-value, with cash out for eligible business expenses. The debt needs 6 months of seasoning and you need 1 year current.
Your likely route: a 504 refinance, up to 90% loan-to-value, fixed.
The refinance rules
Heavy equipment with a long life.
Machinery that will run ten years or more qualifies on the 10 years term. Manufacturers get the program's highest cap: an SBA portion of $5.5 million per project.
Your likely route: a 504 equipment loan on a 10-year term.
504 for manufacturers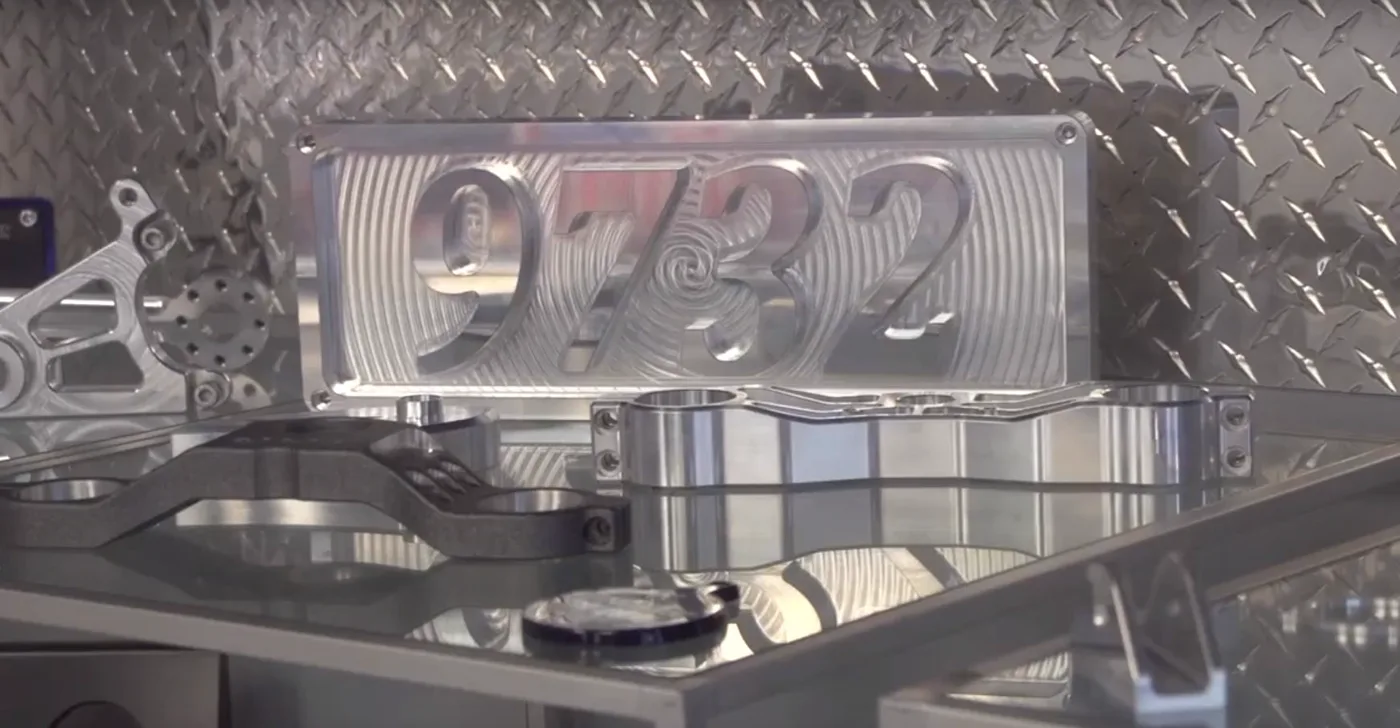
Newer business? Not disqualified. Different.
Operating two years or less, you'll typically put in 15% instead of 10% and the file gets a closer look. Prequalify early, even a year out; knowing the number to build toward is worth more than a yes or no today.
Your likely route: a 504 with 15% down and a closer look at projections.
The start-up rules
Bankers, brokers, CPAs: bring us the deal and keep the relationship.

You hold the first lien on 50% of the project with 10% borrower equity beneath NSDC's position, a better loan-to-value than you'd carry alone, on a customer who stays yours. We take the SBA piece, approve it in-house, and service it for the life of the loan so your borrower never calls you about our half.
What we don't want: pure investment property, working capital only, a business that can't occupy. We'll say so on the first call, which is why the next referral comes.
The math on one building
What $1,000,000 looks like, both ways.
| Conventional | SBA 504 | |
|---|---|---|
| Cash at closing | $250,000 | $100,000 |
| Rate on the larger piece | Resets in 5–10 years | Fixed 25 years |
| Who you deal with after close | Whoever buys the servicing | The same NSDC team |
No cap on the project
The SBA caps only its own share ($5 million). A $10 million building still works.
Fees are financed
roughly 3% of the SBA portion, rolled into the loan, not paid at closing.
Rural counts
Wells, Ely, Elko, Mesquite. Same program, same team, same fixed rate.
Honest about the downsides
More paperwork than a cash deal, and a declining prepayment premium in the early years. The rules.
This month's rates
Set once a month. Fixed for the life of the loan.
Published after each debenture sale, with the month, so you can compare it with anything a bank quotes you.
How the rate is set, and the full tableCurrent SBA 504 loan rates for September 2026
Effective rates as published by NSDC, fixed for the full term once the loan funds. Ten-year (equipment) debentures are sold every other month; ask for the current figure.
You've seen how it works. Now see if it works for you.
If ownership is in the plan, know your options before you sign the next lease. Have handy: the building you have in mind, roughly what it costs, and roughly what the business earns.
Four details, no credit pull. A loan officer in Reno or Las Vegas reads them and calls you. Pre-qualification within three business days.
- Free
- No credit pull
- No documents to start
- A named officer replies
We love owning this because we're in charge of our destiny.
Full Tilt Logistics, NSDC borrower · 2,350+ loans since 1981