Industries
SBA 504 Financing for Healthcare, Medical and Dental Practices
Physicians, dentists and specialty practices across Nevada use SBA 504 loans to own their clinics and finance long-life equipment: as little as 10% down, a rate on the SBA portion fixed for up to 25 years, and the working capital that would have gone into a down payment kept for staff and patient care.
The 504 for Nevada medical practices
Clinics, imaging and the fit-out that goes with them, and what owning does to a practice with a long lease.
Why practices choose a 504
Healthcare economics are their own thing: staffing costs, reimbursement pressure, and technology and compliance spending all compete for the same cash. A 504 moves the largest fixed cost, the building, onto a payment that doesn't change for the life of the loan, and it does so with a fraction of the cash a conventional commercial mortgage asks for.
What the money can buy
- An existing medical or dental office building, or a new clinic, surgery center or specialty facility built from the ground up
- Expansion: additional operatories, treatment rooms, a surgery or imaging suite
- Tenant improvements and build-outs of owner-occupied space; parking, ADA, utilities
- Long-life equipment: CT, MRI, ultrasound, digital X-ray, dental delivery systems, lab automation, with a useful life of ten years or more
- Eligible refinancing of existing fixed-asset debt
Who qualifies
For-profit practices that will occupy the majority of the building: primary and multi-specialty clinics, dental and orthodontic practices, oral surgery, outpatient surgery centers, behavioral health, physical therapy and rehab, imaging and lab facilities. Note that some medical facilities fall on the SBA's special-purpose list and carry a 15% equity requirement; we'll tell you on the first call whether yours does.
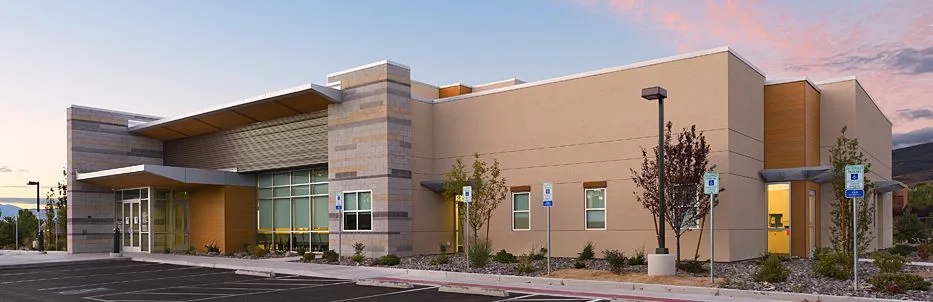
Nevada examples
Nevada practices that own the building they treat patients in.
The structure, whatever the industry
A bank first mortgage, NSDC's fixed-rate SBA portion, and your equity. Start-ups and special-purpose properties put in more.
- 50% Bank or credit union First lien. Its own rate and term.
- 40% SBA 504 through NSDC Second lien. Fixed for 10, 20 or 25 years.
- 10% You Cash or equity you already hold.
Eligibility, in brief
Your business operates for profit; tangible net worth is under $20 million and average net income under $6.5 million; you'll occupy at least 51% of an existing building or 60% of new construction; and the money buys real estate, long-life equipment, or eligible refinancing. The full requirements, with sources.
The timeline
Prequalification is free, with an answer within three business days. Full SBA approval typically takes two to three weeks, and most NSDC loans close within 45 days, because as a Premier Certified Lender NSDC approves in-house. The four phases.
Why NSDC
Nevada's oldest, largest and only statewide CDC, lending since 1981: 2,350+ loans, $1 billion+ in SBA financing, 23,914 jobs supported, from offices in Las Vegas and Reno, serving Nevada, Mojave County, Arizona, and eleven eastern California counties. About NSDC.
This page is for general informational purposes only and does not constitute legal, tax, or financial advice. Figures verified September 2026.
Tell us about the building. We'll tell you where you stand.
Four details, no credit pull. A loan officer in Reno or Las Vegas reads them and calls you. Pre-qualification within three business days.
- Free
- No credit pull
- No documents to start
- A named officer replies
We love owning this because we're in charge of our destiny.
Full Tilt Logistics, NSDC borrower · 2,350+ loans since 1981