Industries
SBA 504 Financing for Logistics, Warehousing and Distribution
Nevada's position between California and the mountain West has made warehousing one of the state's fastest-growing industries, and one where leases reprice hardest. Carriers, 3PLs and distributors use SBA 504 loans to own their warehouses and yards with 10% down and the SBA portion fixed for up to 25 years.
The 504 for Nevada logistics and trucking
Yards, docks and warehouse space, and what happens to the numbers when the rent stops moving.
Why logistics operators choose a 504
A warehouse lease in a tight market is a landlord's asset, not yours. Owning the dock doors, the yard and the square footage your operation depends on removes the one cost that moves fastest, and it turns years of rent into equity in an industrial building that holds value.
What the money can buy
- An existing warehouse or distribution building your operation occupies
- Truck yards, cross-docks and maintenance shops
- Ground-up construction at 60% occupancy
- Dock equipment, racking systems, conveyors and material-handling equipment with a useful life of ten years or more
- Eligible refinancing of existing industrial real-estate debt
Occupancy in a shared building
You can own a building larger than you need today and lease out up to 49% of it, provided your own operation takes 51%. That's how a growing 3PL buys its next five years of space at today's price. The occupancy rules.
Nevada examples
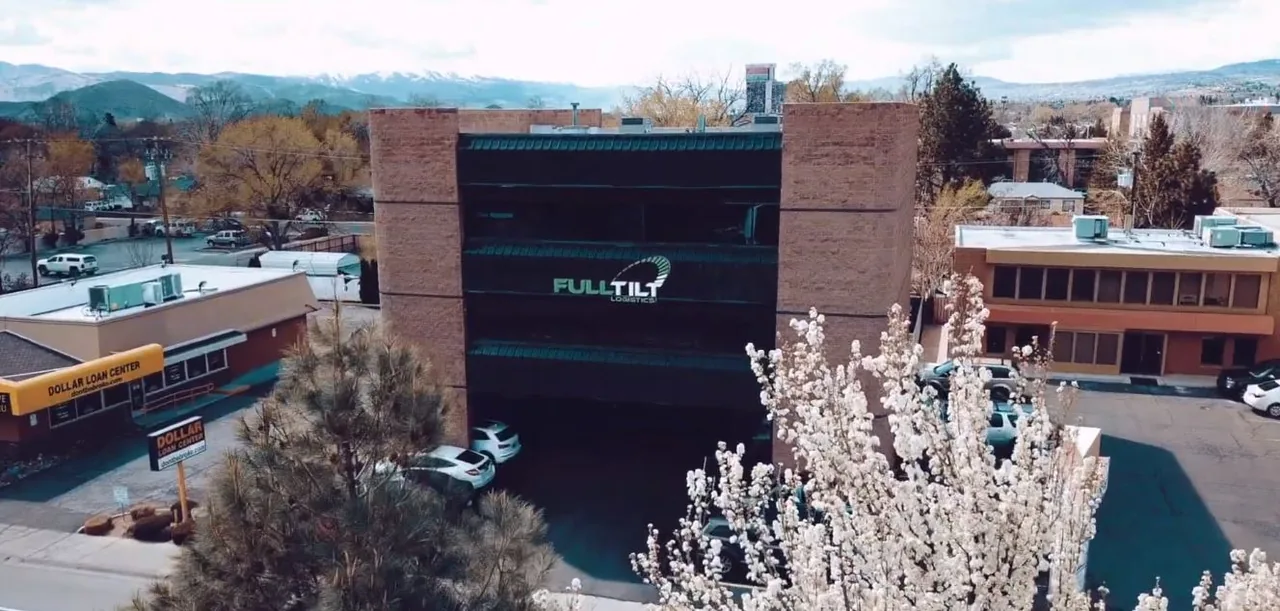
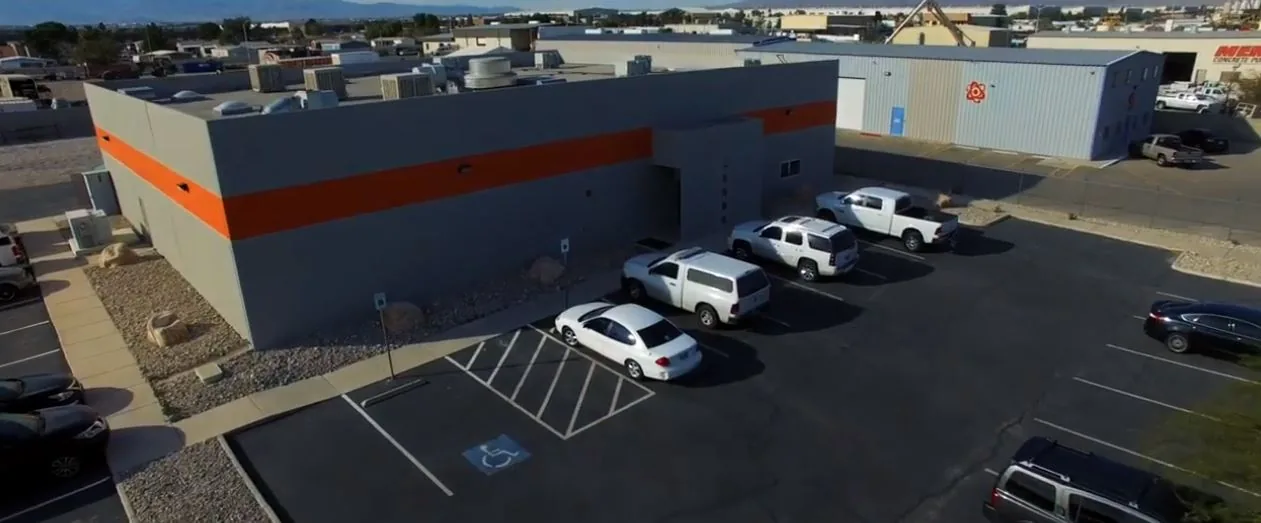
Nevada logistics operators that stopped waiting on a landlord.
The structure, whatever the industry
A bank first mortgage, NSDC's fixed-rate SBA portion, and your equity. Start-ups and special-purpose properties put in more.
- 50% Bank or credit union First lien. Its own rate and term.
- 40% SBA 504 through NSDC Second lien. Fixed for 10, 20 or 25 years.
- 10% You Cash or equity you already hold.
Eligibility, in brief
Your business operates for profit; tangible net worth is under $20 million and average net income under $6.5 million; you'll occupy at least 51% of an existing building or 60% of new construction; and the money buys real estate, long-life equipment, or eligible refinancing. The full requirements, with sources.
The timeline
Prequalification is free, with an answer within three business days. Full SBA approval typically takes two to three weeks, and most NSDC loans close within 45 days, because as a Premier Certified Lender NSDC approves in-house. The four phases.
Why NSDC
Nevada's oldest, largest and only statewide CDC, lending since 1981: 2,350+ loans, $1 billion+ in SBA financing, 23,914 jobs supported, from offices in Las Vegas and Reno, serving Nevada, Mojave County, Arizona, and eleven eastern California counties. About NSDC.
This page is for general informational purposes only and does not constitute legal, tax, or financial advice. Figures verified September 2026.
Tell us about the building. We'll tell you where you stand.
Four details, no credit pull. A loan officer in Reno or Las Vegas reads them and calls you. Pre-qualification within three business days.
- Free
- No credit pull
- No documents to start
- A named officer replies
We love owning this because we're in charge of our destiny.
Full Tilt Logistics, NSDC borrower · 2,350+ loans since 1981