Industries
SBA 504 Financing for Retail Stores and Shopping Centers
A retailer can use an SBA 504 loan to buy or build the building its store occupies, with 10% down and a fixed rate on the SBA portion. The one rule that decides it: your business must occupy at least 51% of the building. The rest can be leased to other tenants. A shopping center you'd lease out entirely doesn't qualify.
The 504 for Nevada retailers
What the loan buys, what you put down, and how the occupancy rule works when you lease out part of the building.
Why retailers choose a 504
Retail lives on location, and location is what a landlord controls. A lease renewal at a number you didn't choose, on a corner your customers know, is the moment most retailers start asking about owning. A 504 fixes the payment on the SBA portion for up to 25 years and keeps the cash a conventional down payment would have taken.
What the money can buy
- The building your store occupies, freestanding or in-line
- A small center where your store takes 51% or more and other tenants take the rest
- Ground-up construction at 60% occupancy, growing to more over time
- Build-out, signage infrastructure, parking, HVAC and refrigeration with a long useful life
- Eligible refinancing of existing retail real-estate debt
Mixed-use, worked
A specialty grocer buys a 10,000 square foot building, occupies 6,000 square feet and leases two 2,000 square foot bays to a cafe and a salon. That's 60% occupancy, comfortably over the line, and the two leases help carry the loan.
What doesn't qualify
A shopping center bought as an investment. A strip you'd lease out entirely. A store you'd sublease. If the plan is to collect rent, that's a conventional investor mortgage, and we'll say so on the first call. Rental property and the 504.
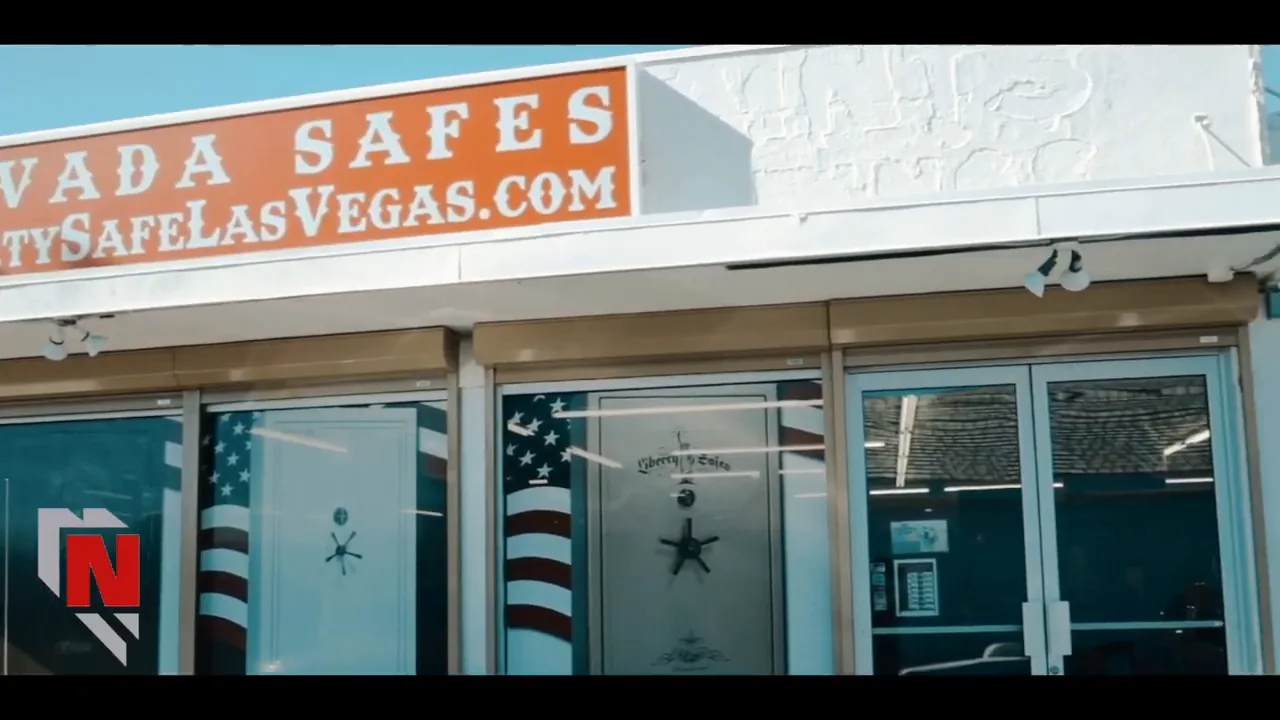
Nevada examples
Nevada retailers that own the corner they trade on.
The structure, whatever the industry
A bank first mortgage, NSDC's fixed-rate SBA portion, and your equity. Start-ups and special-purpose properties put in more.
- 50% Bank or credit union First lien. Its own rate and term.
- 40% SBA 504 through NSDC Second lien. Fixed for 10, 20 or 25 years.
- 10% You Cash or equity you already hold.
Eligibility, in brief
Your business operates for profit; tangible net worth is under $20 million and average net income under $6.5 million; you'll occupy at least 51% of an existing building or 60% of new construction; and the money buys real estate, long-life equipment, or eligible refinancing. The full requirements, with sources.
The timeline
Prequalification is free, with an answer within three business days. Full SBA approval typically takes two to three weeks, and most NSDC loans close within 45 days, because as a Premier Certified Lender NSDC approves in-house. The four phases.
Why NSDC
Nevada's oldest, largest and only statewide CDC, lending since 1981: 2,350+ loans, $1 billion+ in SBA financing, 23,914 jobs supported, from offices in Las Vegas and Reno, serving Nevada, Mojave County, Arizona, and eleven eastern California counties. About NSDC.
This page is for general informational purposes only and does not constitute legal, tax, or financial advice. Figures verified September 2026.
Tell us about the building. We'll tell you where you stand.
Four details, no credit pull. A loan officer in Reno or Las Vegas reads them and calls you. Pre-qualification within three business days.
- Free
- No credit pull
- No documents to start
- A named officer replies
We love owning this because we're in charge of our destiny.
Full Tilt Logistics, NSDC borrower · 2,350+ loans since 1981